If you are buying in Charlottesville, Albemarle County, Crozet, Waynesboro, or Staunton and a conventional loan does not fit your credit, income documentation, down payment, or loan size, you have real options. Which one you get depends on who is shopping the programs for you. I chose these providers on how many non-conventional programs they offer, how they handle self-employed, foreign national, and lower-credit borrowers, and how well they know the UVA-driven local market. Cavalier Mortgage sits first because it is my own shop, and I describe its limits as plainly as the others.
By Duane Buziak, NMLS #1110647
Quick Comparison of the Six Providers
- Cavalier Mortgage by Duane Buziak: borrowers whose credit, income documentation, or residency rules out conventional; pricing quoted per borrower; shops 500+ wholesale partners across government and non-QM programs at once.
- Atlantic Coast Mortgage (Jenna Stiltner): standard-profile buyers who want a well-known local retail loan officer; pricing on request; the strongest realtor name recognition in Charlottesville.
- First Heritage Mortgage: buyers who want a team-supported retail process; pricing on request; several local originators in one office.
- Prosperity Home Mortgage: buyers who want a large national company with local contact; pricing on request; an established national branch network.
- Movement Mortgage: buyers who value national scale and in-house servicing; pricing on request; one company handling origination and servicing.
- Alcova Mortgage: Virginia buyers who prefer a regionally focused company; pricing on request; a Virginia-market focus, with local presence to be confirmed.
1. Cavalier Mortgage by Duane Buziak
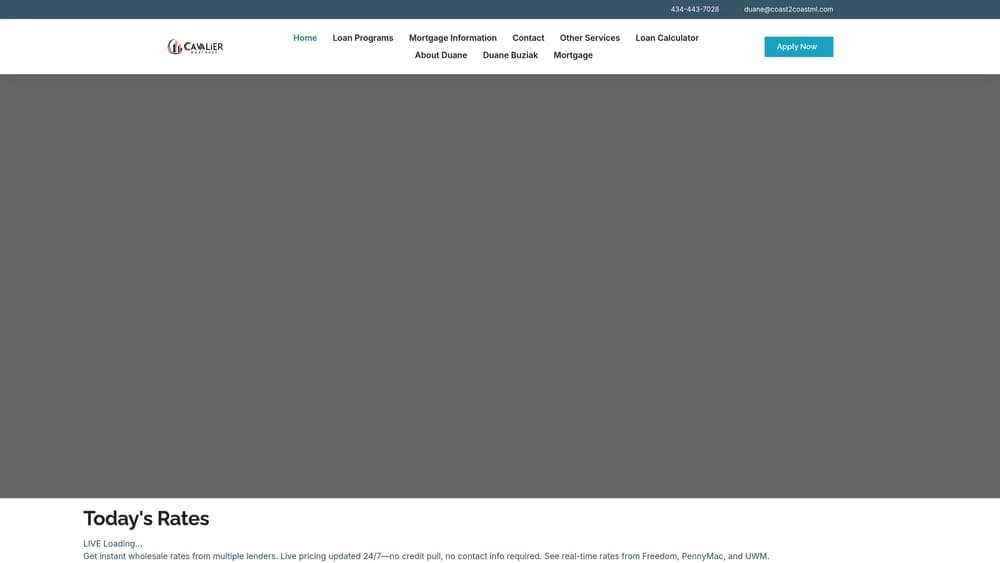
Cavalier Mortgage is an independent Charlottesville mortgage brokerage. I place FHA, VA, USDA, jumbo, DSCR, non-QM, bank statement, asset depletion, and ITIN/foreign national loans with whichever of 500+ wholesale partners fits the file. It is built for borrowers who have been told “not conventional” and want to know what the next move is.
The distinctive part is simultaneous shopping across both government and non-QM programs. A retail shop can only run your file through its own guidelines. I can compare the same borrower across dozens of rule sets in one pass, which matters most when the file has an edge: a 520 FICO veteran, a self-employed buyer with heavy write-offs, or a foreign national buying near Grounds.
- VA loans down to a 500 FICO, so a veteran with a rebuilding credit history is not turned away on score alone.
- Bank statement, DSCR, and asset depletion programs that qualify you on deposits, rental income, or assets instead of tax returns.
- ITIN and foreign national programs for buyers without a Social Security number or U.S. credit history.
- Dynamo DPA and Turbo DPA down payment assistance, which can reduce the cash you bring to closing.
- Cash-out refinancing up to 90% of value for owners tapping equity.
- NoTouch Credit Pull, a soft credit pull mortgage pre-approval option, so you can see where you stand with no hard inquiry before committing.
Setup is light. I run the file myself, coordinate with your realtor and UVA-area relocation contacts, and place the loan with a wholesale partner. You deal with one person, and I am reachable around the clock.
The limitation is structural. As a broker, I do not fund or service the loan in-house. It closes with a wholesale partner and may be serviced elsewhere, so you will not have one company’s name on every statement. Some buyers prefer that single-company relationship, and a clean-profile borrower may not need a broker’s reach at all.
Pricing is quoted per borrower; see the website. Rate and cost depend on credit score, down payment, loan amount, occupancy, and program, and no rate is guaranteed until the file is underwritten.
Best for: Borrowers whose credit, income documentation, or residency status rules out conventional.
2. Atlantic Coast Mortgage (Jenna Stiltner)
Atlantic Coast Mortgage is a retail mortgage company, and Jenna Stiltner is the loan officer most often named in Charlottesville realtor circles. That name recognition is real and useful: listing agents know her, and a familiar name on a pre-approval letter can smooth an offer in a tight market.
What it does best on this list is local referral standing. If your profile is standard and you want someone your agent already trusts, that counts for something.
- FHA, VA, and USDA options, so lower-down-payment buyers have a path. Confirm the current program list on the official site.
- Established local realtor relationships that can help communication during a competitive purchase.
- Retail underwriting under one company, which keeps processing and decisions inside a single organization.
The trade-off is the shelf. A retail loan officer works inside one institution’s product set, rate structure, and underwriting guidelines. For a clean conventional or FHA file, that can be perfectly adequate. For a VA loan to a 500 FICO, a DSCR investor loan, a bank statement file, or a rate-shopping scenario, you should confirm whether the company offers the program at all. Ask directly about non-QM and foreign national availability, because I could not verify it for this list.
Integrations and setup are not published in detail, so check the official site. Expect a standard retail process with the loan officer and processing team handling the file.
Pricing is on request. Cost moves with credit score, down payment, loan size, and the program chosen.
Best for: Standard-profile buyers who want a well-known local retail loan officer.
3. First Heritage Mortgage
First Heritage Mortgage is a retail mortgage company with several local loan officers serving the Charlottesville area. Its distinguishing trait here is team coverage: more than one originator, so there is usually someone to pick up the file when your primary contact is out.
What the team model gives you
- FHA, VA, and USDA options for borrowers who need lower down payments. Verify the current menu on the official site.
- A multi-originator team, which can mean quicker responses and less dependence on one person’s calendar.
- Jumbo financing for higher price points, which matters in Albemarle where many purchases clear the conforming limit. Confirm availability and terms directly.
Where it runs out
It is a single-company menu. Every loan runs through one set of guidelines and overlays, and specialty non-QM programs such as bank statement, DSCR, asset depletion, or ITIN options need to be confirmed before you assume they exist. If a program is missing, the team cannot send the file elsewhere the way a broker can.
Day to day, the loan officer and support staff run the process in-house. I could not verify technology integrations, so ask how documents are collected and how often you will get status updates.
If you are self-employed with a heavily written-off return, a foreign national, or a buyer with a score well below 600, ask for written confirmation of the specific program and its credit floor before you invest time in an application.
Pricing is on request, and it varies with credit, down payment, loan amount, and occupancy.
Best for: Buyers who prefer a team-supported retail process.
4. Prosperity Home Mortgage
Prosperity Home Mortgage is a national retail mortgage company with a Charlottesville-area loan officer. Its calling card is scale: an established branch network and the operational depth that comes with a large national platform.
For a buyer relocating to UVA from another state, that can be reassuring. A national company can sometimes coordinate across locations if you are selling in one market and buying in another.
- Government loan programs, which give lower-down-payment buyers FHA, VA, and USDA paths. Confirm specifics on the official site.
- Jumbo options for loans above the conforming limit, which is relevant for many Albemarle purchases. Verify current terms and requirements.
- A national branch network, which can help when the transaction spans more than one state.
The limitation is breadth versus a wholesale broker. A national retail company still has one product menu and one underwriting culture. I could not verify how deep its specialty offerings run for DSCR, bank statement, asset depletion, or foreign national borrowers, so treat those as questions to put to the loan officer in writing. Company-level overlays can also be stricter than the minimums set by FHA or VA, which is where lower-credit borrowers tend to hit walls.
Setup follows a typical national retail workflow: an application, a loan officer, and a processing and underwriting team that may sit outside Charlottesville. Ask who your daily contact will be and where underwriting happens, since local knowledge matters with UVA-driven inventory and appraisal quirks.
Pricing is on request. Credit score, down payment, loan size, and program drive the quote.
Best for: Buyers wanting a large national company with local contact.
5. Movement Mortgage
Movement Mortgage is a large national retail mortgage company that originates and services loans in-house. That combination is its clearest advantage on this list: the company that closes your loan can also be the one you pay each month, with no servicing transfer to a different company.
The program menu is broad for a retail shop, and that scale gives it consistent processes and brand recognition across many markets.
- FHA, VA, and USDA loans, so buyers with modest down payments or military service have established options. Confirm the current list.
- Down payment assistance offerings, which can matter for first-time buyers. Verify what is available in Virginia and who qualifies.
- In-house servicing, which keeps customer service and payment handling under one roof after closing.
The limitation is the other side of the same coin. One company’s guidelines and overlays apply to every loan. If your file does not fit, you cannot ask the company to run it elsewhere. A borrower with a 540 FICO, bank statements instead of tax returns, or a rental property to finance on DSCR should ask early whether the product exists, and at what credit floor.
Integrations are not something I could confirm, so check the official site for its online application and document portal. Day-to-day work is run by the local loan officer and a national operations team, so ask where your processor and underwriter sit.
If you like the idea of one company from application through payoff, this is the model that delivers it. If your priority is the widest program choice, it is not.
Pricing is on request, shaped by credit, down payment, loan size, and program.
Best for: Buyers who value national scale and in-house servicing.
6. Alcova Mortgage
Alcova Mortgage is a mortgage company with a Virginia presence. I could not confirm how large its Charlottesville footprint is, so verify that on the official site before counting on face-to-face local service.
Its draw is regional focus. A company centered on Virginia may know state-specific details, from local closing practices to how county-level appraisals behave, better than a national platform that treats Virginia as one market among fifty.
- FHA, VA, and USDA options for buyers who need low-down-payment financing. Verify the current program menu directly.
- Virginia market familiarity, which can help with local appraisal and title expectations. Ask for examples of recent Charlottesville-area closings.
- Possible specialty programs, though availability needs confirmation. Do not assume non-QM, DSCR, or foreign national options exist until you have them in writing.
The limitations are the ones the research could not resolve. Local presence and specialty program depth both need confirmation, and until you have it, you are shopping a single company’s menu. That is the same structural constraint every retail option here shares, and it is the main reason a borrower with an unusual file should ask a broker to compare the market.
On setup, expect a conventional application and processing workflow handled by the company’s loan officers and staff. Ask who will handle your file and whether that person works in the Charlottesville area, because tight UVA-driven inventory leaves little room for slow communication.
Pricing is on request. Credit score, down payment, loan amount, and occupancy move the quote.
Best for: Virginia buyers who prefer a regionally focused company.
Which Option Fits Which Borrower
- Lower credit: FHA allows 3.5% down at 580 or above and 10% down for 500 to 579 per HUD. VA has no official minimum score, and my wholesale partners include programs that accept a 500 FICO. A broker’s reach matters most here.
- Self-employed: Bank statement loans qualify you on deposits, not on a tax return reduced by write-offs. Ask whoever you use whether the program exists in their shelf.
- Investor: DSCR loans qualify on the property’s rent against its payment, not your personal income.
- Foreign national: ITIN and foreign national programs are specialty products. Expect larger down payments, and confirm availability before applying anywhere.
- Thin down payment: VA and USDA can mean no down payment where you qualify, and DPA such as Dynamo and Turbo can cover part of the cash. USDA eligibility depends on the property’s location and household income, so check the USDA map for rural Albemarle and Crozet addresses.
- Jumbo: Loans above the conforming limit need jumbo financing, and many Albemarle purchases land there.
My standout picks: Cavalier Mortgage for any file with an edge, Atlantic Coast Mortgage for a clean profile where realtor familiarity helps, and Movement Mortgage for buyers who want origination and servicing under one roof. If you are unsure which category you fall into, a soft pull mortgage broker conversation costs you nothing on your credit file. Whether you are a first-time buyer, UVA faculty member, or exploring non-traditional loan options, Duane Buziak and Cavalier Mortgage deliver broker-superior solutions 24/7, shopping 500+ wholesale lenders to secure terms retail banks simply can’t match. Get your personalized rate quote now and discover why over 1,400 five-star reviews have made us Virginia’s consecutive VA Broker of the Year.