If you need a mortgage along the I-64 corridor between Staunton and Charlottesville, you want an independent broker who shops hundreds of wholesale lenders, not a loan officer limited to one company’s products. Most people search for an “I-64 corridor Virginia mortgage lender,” but the broker-versus-lender distinction is the whole point. A broker like me places your loan with whichever wholesale lender prices your file most competitively.
The corridor is not one market. Staunton, Waynesboro, Crozet, Albemarle County and Charlottesville differ in price, buyer profile and the loan program that fits. Below I walk the corridor west to east, match programs to each stretch, work through a dollar example, compare the main local options in a table, and show how to compare offers with a soft credit pull so your score stays intact.
How the I-64 Corridor Ties Five Markets Together, Staunton to Charlottesville
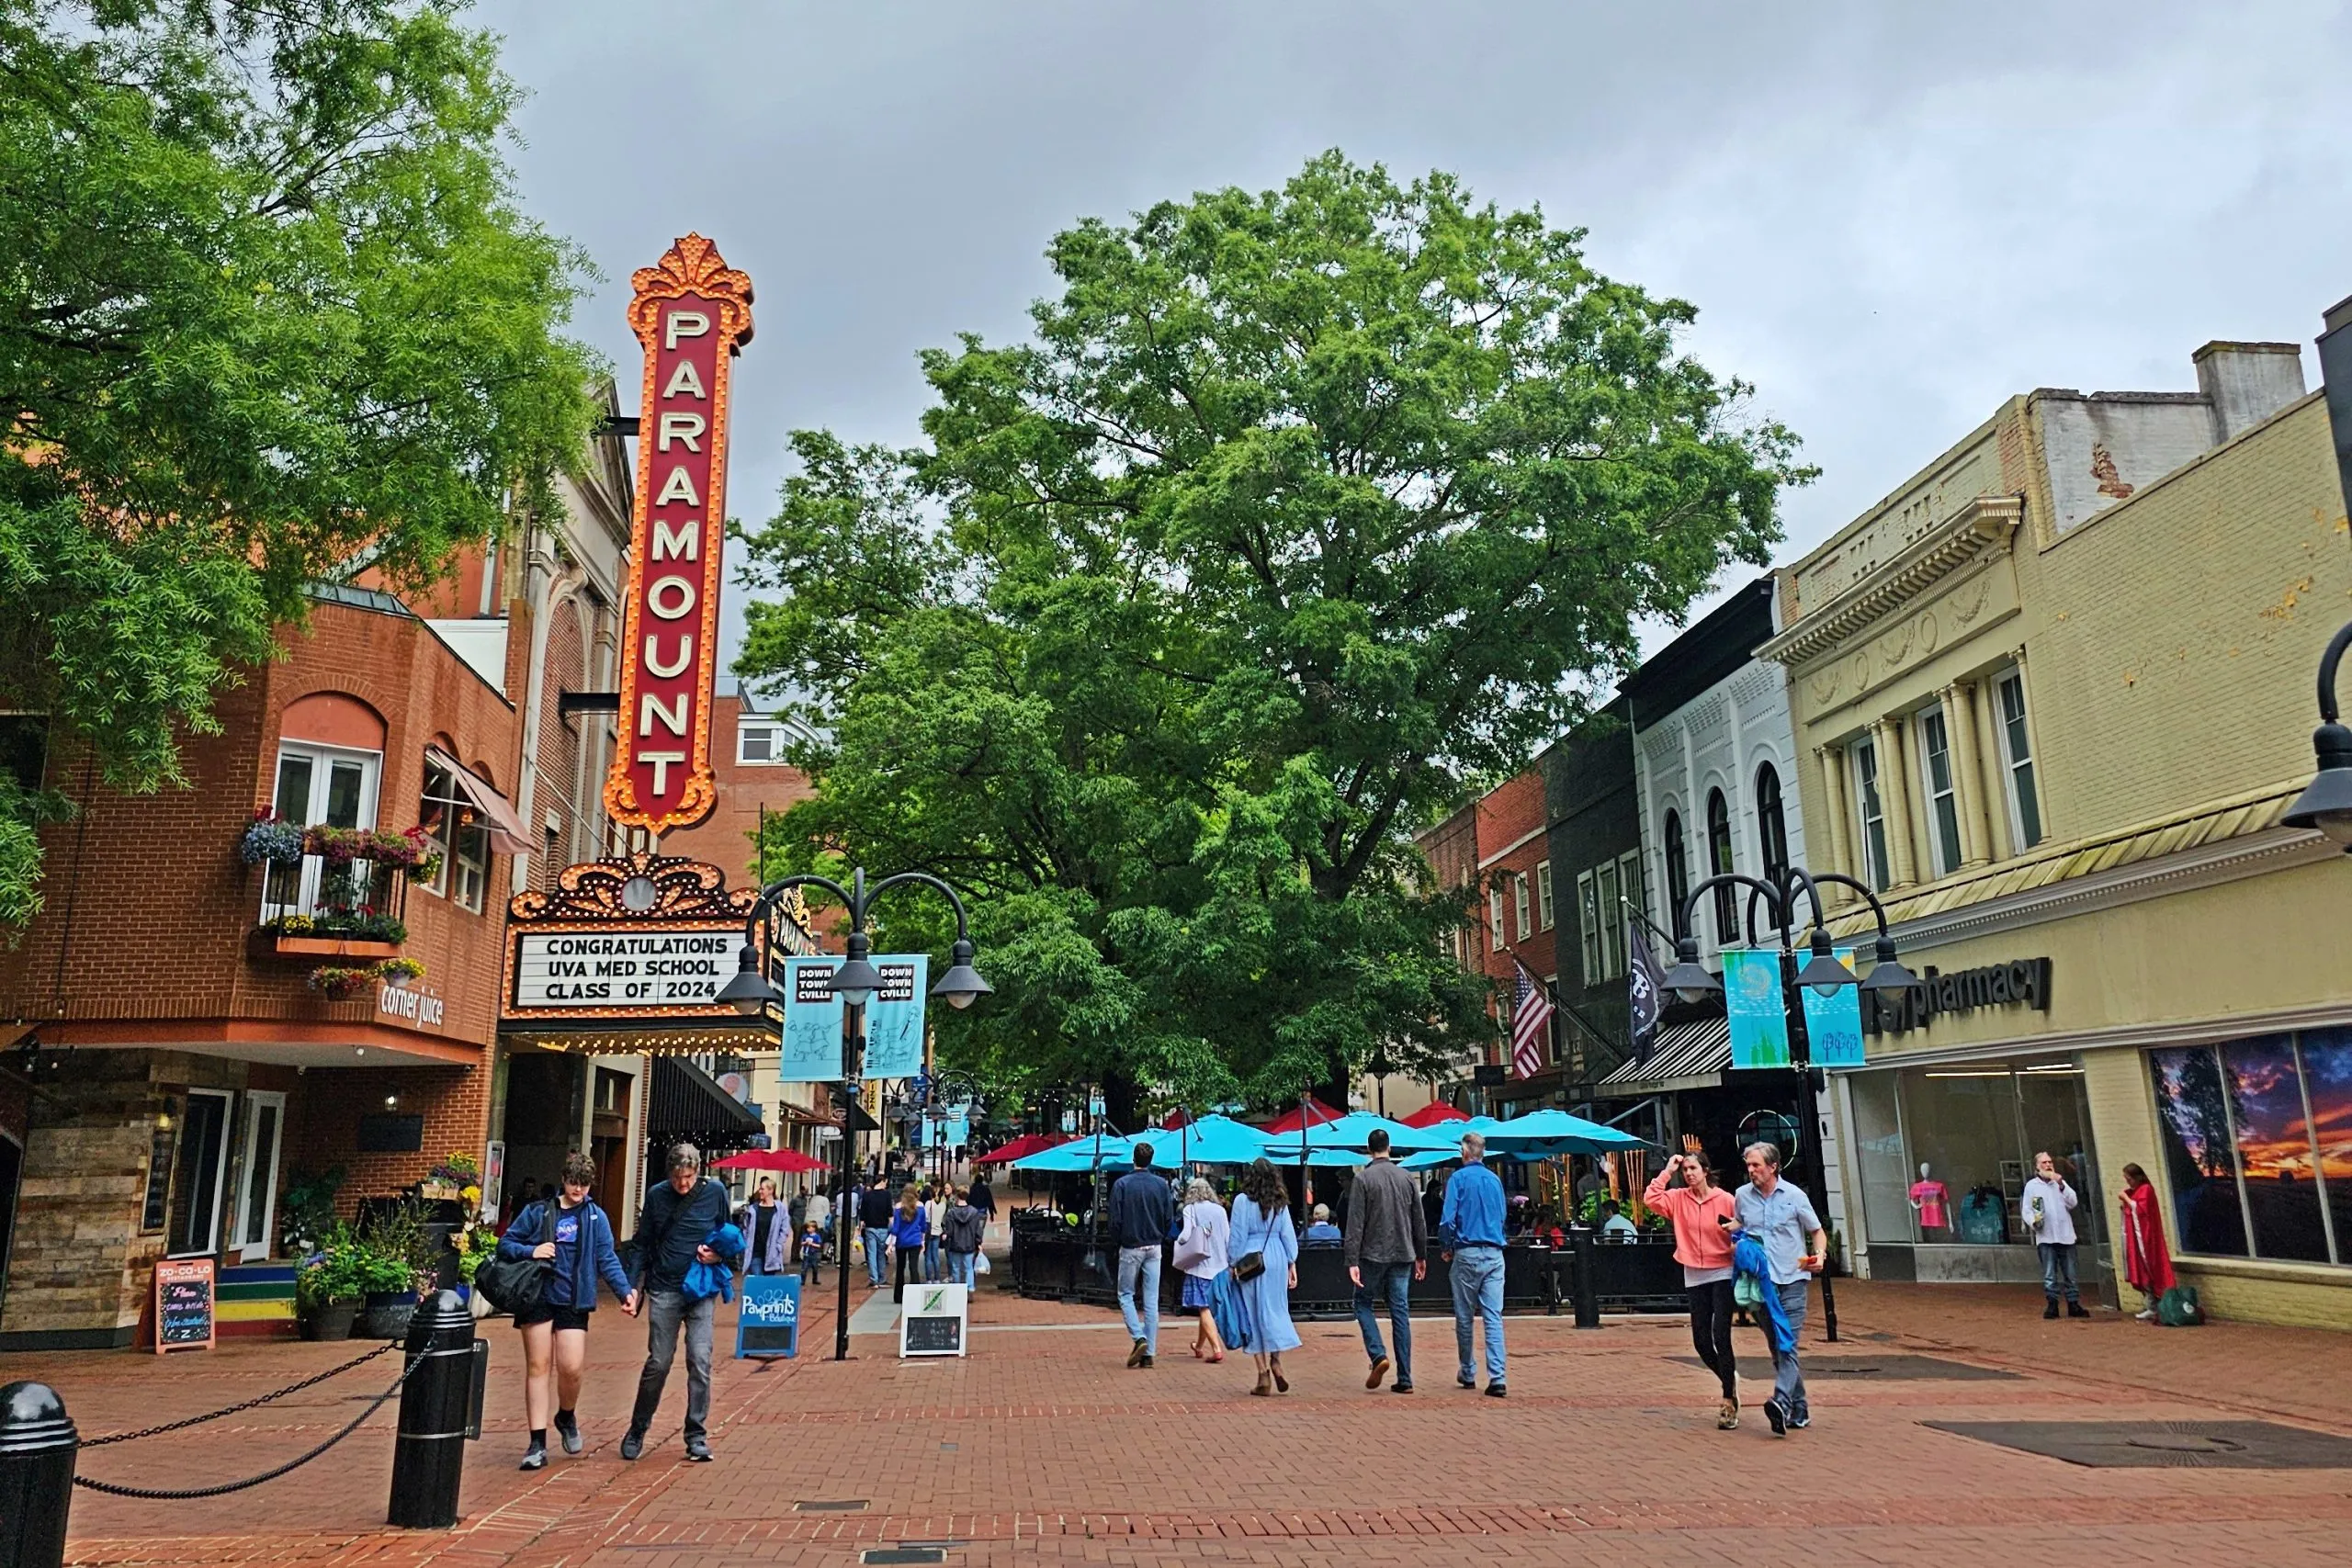
Drive east on I-64 and the buyer profile changes with each exit. Staunton and Waynesboro draw first-time buyers and households trading city prices for space. Crozet, reached from I-64 via Afton and Route 250, is a growth pocket of newer construction popular with UVA-connected families. Albemarle County runs from in-fill neighborhoods to rural estates. Charlottesville itself, with UVA at its center, carries the highest price tier and the most competition.
That gradient drives behavior. Buyers priced out near the University look west, accepting a longer commute for more house per dollar. As the zip code changes, so does the loan that fits. A first-time buyer in Waynesboro may be a natural FHA or down-payment-assistance candidate, while an Albemarle estate purchase can push into jumbo territory.
For a local price anchor, Zillow Research publishes monthly home value data by metro and city. The pattern is consistent: Charlottesville and Albemarle sit well above Waynesboro and Staunton. Pull the current Charlottesville figure and the “as of” month before you set a budget, because it moves every month and I will not quote a stale number.
One definition matters before anything else. A mortgage broker such as Duane Buziak places your loan with a wholesale lender chosen from hundreds, based on which one fits your file and prices it best. A retail loan officer can offer only their employer’s products, rates and underwriting rules. Neither is wrong for every borrower, but only one of them can change lenders when your scenario changes.
Which Loan Program Fits Which Stretch of I-64
Conventional and FHA cover most Waynesboro and Staunton first-time purchases. FHA, backed by HUD, accepts lower credit scores and smaller down payments than many conventional options. Down payment assistance such as Dynamo DPA and Turbo DPA may layer on top, but eligibility depends on the specific program and the borrower, so I confirm it against your file before you count on it.
USDA works for eligible addresses outside the urban core, which can include properties around Crozet, Waynesboro and Staunton. Eligibility is address-specific, so check the property, not the town, on the USDA eligibility map before you fall for a house.
VA loans serve veterans and active-duty buyers across the whole corridor. Through my wholesale shelf, options can reach down to a 500 FICO, though each wholesale lender sets its own overlays, so the path depends on the file. Borrowers with full VA entitlement have no VA loan limit, as described on the VA home loans page. I was named VA Broker of the Year for 2024 and 2025 consecutively because VA files are where broker independence pays off most.
Jumbo loans matter at Albemarle estate and upper Charlottesville price points. As of 2026, the baseline conforming limit is $832,750 per FHFA’s annual announcement, and I would confirm the county’s treatment there. When your loan amount exceeds the limit for your county, you need jumbo pricing and underwriting, and that is a very different rate conversation.
Non-QM products fill the gaps that standard underwriting leaves:
- Bank statement loans for self-employed buyers whose tax returns understate cash flow.
- DSCR loans for investors qualifying on a rental property’s income.
- Asset depletion for buyers with large savings but little current income.
- ITIN and foreign national loans for UVA faculty on visas and international buyers.
Worked Example: A $525,000 Albemarle Purchase at Two Rates
These rates are hypothetical and illustrative, not a quote. Suppose you buy a $525,000 home in Albemarle County with 10% down ($52,500), leaving a $472,500 loan on a 30-year fixed term.
- At 6.25%: principal and interest is about $2,909 per month.
- At 6.00%: principal and interest is about $2,833 per month.
The gap is roughly $76 per month, which adds up to about $27,500 over 360 payments if you hold the loan to term. Those figures come from the standard amortization formula, payment = P × r ÷ (1 − (1 + r)^−n), with a monthly rate of rate ÷ 12 and 360 payments.
Principal and interest is not your whole payment. For illustration, assume a property tax rate near $0.85 per $100 of assessed value, which on $525,000 is about $4,460 a year, or $372 a month. Assume homeowners insurance of $1,800 a year, or $150 a month. Check the current rate and its effective date on the Albemarle County website, since the board of supervisors can change it. Mortgage insurance, which a 10% down conventional loan typically carries, is not included here and varies with credit score.
- All-in at 6.25%: about $3,431 per month before mortgage insurance.
- All-in at 6.00%: about $3,355 per month before mortgage insurance.
A quarter-point spread is exactly what one extra comparison can surface. Different wholesale lenders price the same borrower differently on the same day, which is the practical reason to look beyond a single source.
I-64 Corridor Mortgage Comparison: Cavalier Mortgage vs. Atlantic Coast, Movement and Alcova
This comparison is factual and meant to show structural differences, not to start a rate war. Where I cannot verify a competitor detail from public sources, the cell says to confirm on the company’s site.
| Factor | Jenna Stiltner / Atlantic Coast Mortgage | Movement Mortgage | Alcova Mortgage | Duane Buziak, NMLS #1110647 (Cavalier Mortgage) |
|---|---|---|---|---|
| Business model | Retail lender; loan officer works within one institution’s guidelines | Retail lender; confirm on company site | Retail lender; confirm on company site | Independent mortgage broker |
| Where the loan is placed | The employer’s own product set and rate sheet | Confirm on company site | Confirm on company site | Hundreds of wholesale lenders, chosen per file |
| FHA, VA, USDA | Confirm on company site | Confirm on company site | Confirm on company site | All three, with VA options down to 500 FICO (wholesale overlays vary) |
| Jumbo | Confirm on company site | Confirm on company site | Confirm on company site | Yes, shopped across wholesale lenders |
| Non-QM (bank statement, DSCR, asset depletion, ITIN/foreign national) | Confirm on company site | Confirm on company site | Confirm on company site | Yes, all four categories |
| Soft-pull pre-approval | Confirm directly | Confirm directly | Confirm directly | NoTouch Credit Pull, a soft credit pull review before any hard inquiry |
| Availability | Confirm directly | Confirm directly | Confirm directly | 24/7 |
| Local presence | Well known in Charlottesville Realtor circles | Confirm on company site | Confirm on company site | Charlottesville-focused, serving Staunton through Albemarle |
A single-company loan officer is a reasonable fit for a clean conventional purchase with strong credit and standard W-2 income, where one institution’s pricing may be competitive. A broker’s shelf matters more when you have credit challenges, self-employed income, a jumbo balance or foreign national status, because those files often succeed with one wholesale lender and fail with another.
There is also a persistent assumption that a bank is the safer choice. Safety comes from the Loan Estimate, the closing disclosure and regulation of the transaction, not from the logo on the letterhead. Broker and retail loans alike are governed by the same federal disclosure rules.
Comparing Offers Without Hurting Your Credit
Start with a soft credit pull. With NoTouch Credit Pull, I review your credit through a soft pull mortgage process and show you real options with no hard inquiry at the pre-approval stage. That gives you mortgage pre-approval without a hard pull before you commit to anything. Be clear on one point: a formal application eventually requires a hard credit check, and I will tell you when that moment arrives.
Shopping itself is safer than most people fear. Credit scoring models generally treat multiple mortgage inquiries made within a short window as a single inquiry, with the window varying by model, roughly 14 to 45 days. The CFPB’s rate-shopping guidance covers how this works, and you should read its exact window language before you start applying around.
That is what Dare to Compare is for. Bring me any written Loan Estimate from another source and I will compare it with mine line by line. The CFPB’s Loan Estimate explainer shows which boxes matter. Focus on these:
- The interest rate and the points paid to get it.
- Origination and other lender fees in the Loan Costs section.
- The APR, which folds many costs into one comparable percentage.
- Cash to close, after any credits.
The most common mistake is comparing only the rate. A lower rate bought with extra points can cost more over the years you actually hold the loan, so the lowest rate is not always the lowest cost. If upfront cash is the constraint, ask about no-out-of-pocket closing options, which structure credits so you bring less to the table. That is a different thing from claiming closing costs disappear, because they never do. Someone pays them.
Corridor Mortgage Questions, Answered
Who is an I-64 corridor mortgage broker near Charlottesville?
Duane Buziak, NMLS #1110647, is an independent mortgage broker serving Staunton, Waynesboro, Crozet, Albemarle County and Charlottesville. He shops hundreds of wholesale lenders on each file, offers a soft-pull review, and is available 24/7 at 434-443-7028.
What is the difference between a broker and a bank or lender in Charlottesville?
A broker places your loan with a wholesale lender picked from hundreds, so the product and pricing change to fit your file. A bank or retail lender offers only its own products and underwriting rules. For simple files either can work; for complex ones, a broker’s range matters more.
Does rate shopping hurt your credit score?
Not much when done in a short window. Scoring models generally count multiple mortgage inquiries in a brief period as one, and the CFPB explains the rate-shopping approach. The exact window varies by scoring model, so keep your comparisons within a few weeks.
Can I get pre-approved with a soft pull?
Yes, for the review stage. Through NoTouch Credit Pull, I assess your options with a soft credit pull and no hard inquiry, so you see realistic terms first. A hard credit check is still required when you submit a formal application, and I tell you before that step.
Is USDA available around Crozet, Waynesboro or Staunton?
It can be, but eligibility depends on the property address, not the town. Enter the specific address in the USDA eligibility tool. Borrower income and other program rules also apply, and I review those with you before you make an offer.
What is the 2026 conforming loan limit, and when do I need a jumbo?
As of 2026, the baseline conforming limit is $832,750, per the FHFA announcement. When your loan amount exceeds the limit that applies to your county, you need jumbo financing. Down payment size changes your loan amount, so it changes which side of the line you land on.
Can UVA faculty on visas or international buyers get a mortgage?
Often yes. ITIN and foreign national programs exist for buyers without a Social Security number or with limited U.S. credit history. Terms, down payment and documentation vary by wholesale lender, and I match your situation to the program that accepts it.
Can I get a VA loan with a low credit score?
Sometimes. The VA home loan program sets no minimum score itself, and through my wholesale shelf there are options down to a 500 FICO. Individual wholesale lenders set their own overlays, so approval depends on the full file.
Call Duane for a Soft-Pull Review Before You Pick an Exit
The corridor rewards buyers who compare. A Staunton first-time purchase, a Crozet new build and an Albemarle estate each call for a different program, and the quarter-point gap in the worked example is the kind of difference a second look can find. Call Duane Buziak at 434-443-7028 for a soft-pull review, and bring any Loan Estimate you already have.
Whether you’re a first-time buyer, UVA faculty member, or exploring non-traditional loan options, Duane Buziak and Cavalier Mortgage deliver broker-superior solutions 24/7, shopping hundreds of wholesale lenders to secure terms retail banks simply can’t match. Get your personalized rate quote now and discover why over 1,400 five-star reviews have made us a consecutive VA Broker of the Year.